October’s biggest story was the question of who will own De Beers. Richemont and Signet entered talks to join the Global Diamond Consortium’s bid to buy the miner from Anglo American, joining Namibia, Angola and private investors already involved, while Botswana negotiated to raise its own stake in the consortium to about 25%. Mining output kept shrinking elsewhere: Rio Tinto’s rough diamond production fell 68% year over year to 1.1 million carats over the nine months through September, after its last active mine, Diavik in Canada, closed in March. Petra Diamonds said it was weighing a sale of its business amid financial strain, and Mountain Province handed its stake in the Gahcho Kué deposit to De Beers. US jewelry trade health kept improving too: the Jewelers Board of Trade counted 116 business closures in the third quarter, down from 126 a year earlier, even as the total number of active companies slipped 1.4% year over year to 21,831.
Dubai’s DMCC convened its seventh Dubai Diamond Conference as part of the second Dubai Diamond Week, unveiling an 888.88 carat rough diamond and announcing a new partnership with HRD Antwerp as part of a declared strategic reset for the natural diamond sector. India’s Titan Company incorporated a wholly owned Canadian subsidiary to bring its Tanishq jewelry brand into Canada, extending a retail push that already spans the UAE and the US. On personnel, Frederick Goldman promoted Bryan Cowan to chief operating officer and Tom Schwartz to chief marketing officer on October 5, a restructuring that coincided with the departure of longtime president John Orrico. Rapaport made its own leadership move on October 15, naming former Perion Network chief technology officer Yosi Botzer as its new CTO to lead a company wide push into artificial intelligence across Rapaport Trade properties, including the Rapaport Price List and tools such as its Ring Builder design feature.
Here’s your diamond market analysis from Rapaport Trade for November 2026
Prices for 1.00 to 1.49 carat diamonds softened in October. D-F led the decline: IF-VVS fell 1.5%, up from a 0.4% gain last month, VS fell 0.6% versus -0.3%, and SI fell 1.4% versus -0.9%. G-J was flat, with IF-VVS at 0.0% versus 0.6% and VS at -0.1% versus 0.7%. G-J SI rose 0.3%, versus -0.6% in September. K-M IF-VVS and VS averaged 1.1%, down from 1.9%.
The largest swing was K-M VS, which fell 0.6% after rising 3.9% in September. K-M IF-VVS moved the other way, gaining 2.8% versus -0.2%. K-M SI slipped 0.1%, versus -0.2%.
Inventory shifted toward G-J. G-J now makes up 62.9% of listings, up from 62.1%. D-F fell to 30.8% from 31.2%, and K-M fell to 6.3% from 6.6%. G-J VS grew to 25.1% of inventory from 24.3%, and G-J SI grew to 16.9% from 16.7%. G-J IF-VVS slipped to 19.4% from 19.6%.
Buyer searches stayed concentrated in the same two categories. G-J VS led with 23.1% of searches, versus 22.5% in September. D-F IF-VVS followed at 19.4%, versus 19.5%. The gap between the top two widened to 3.7 points from 3.0. D-F VS held third at 17.5%, versus 17.9%. G-J SI searches rose to 12.2% from 11.4%, and G-J IF-VVS searches fell to 14.5% from 15.0%.
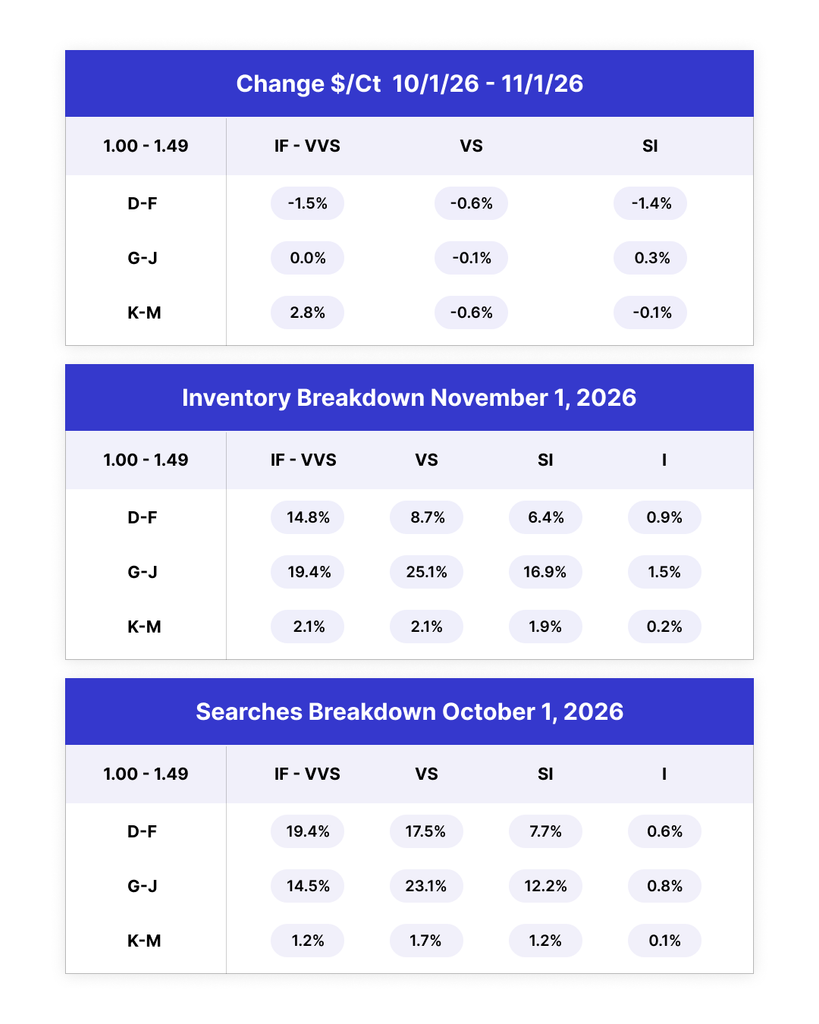
Please note: the searches breakdown are a breakdown of buyers searches on Rapaport Trade
<<Click here>> to join the industry’s largest and most trusted
diamond, gem and jewelry trading network.