News: Trading seasonally quiet during summer lull. Lack of sales to Far East weakening sentiment, with US demand supporting market. Increasing concern about impact of inflation and higher interest rates on mid-income consumers. Holiday outlook positive. Manufacturers maintaining lower production due to slowdown in orders. Polished trading sluggish. Rough prices stable at De Beers sight; premiums drop to around 2% on secondary market, leaving little room for profit. Gem Diamonds 1H revenue -4% to $100M, average price -7% to $1,745/ct. Brilliant Earth 2Q sales +18% to $109M. Sarine launches automated in-factory grading. Pandora to roll out lab-grown collection in US on Aug. 25.
Fancies: Market has cooled for 0.30 to 1.20 ct. diamonds. Supply shortages of well-cut fancies supporting prices. 1.20 to 3.99 ct., F-J, VS-SI goods stable. Oval is leading shape, followed by Radiant, Emerald, Pear, Cushion and Marquise. Retailers offering broader product ranges as consumers seek alternative cuts. Growing interest in fancy-shape engagement rings. Oversizes trading at higher prices than usual. Excellent shapes commanding premiums. Off-make, poorly cut fancies illiquid and difficult to sell.
United States: Market improving after summer slowdown. Trade optimistic for holiday season. Overseas suppliers holding prices firm. Steady memo demand for 3X round, 1.20 ct.+, F-H, VS-SI goods. Stones above 2 ct. performing better than smaller sizes, reflecting reduced mid-market sales due to inflation. Some improvement in 1 ct. segment.
Belgium: Slow activity during vacation period with bourses still closed for summer. Rough trading reduced during De Beers sight week due to concern about consumer demand; rough premiums declining.
Israel: Diamond exchange on summer break, with few dealers present. Optimism for holidays as US demand remains solid.
India: Short week due to 75th Independence Day. US orders supporting trade during summer lull in Belgium and Israel. Limited sales to China, which is still suffering effects of Covid-19 lockdowns. Some US buyers reporting high asking prices and limited discounts. Polished production remains low due to uncertain demand and shortages of Russian rough. Titan reports increase in market share and notes rise in sourcing costs since November 2021 because suppliers have increased prices.
Hong Kong: Market continues to improve. Local sentiment picking up as coronavirus situation eases. China slow. Jewelers increasing inventory levels gradually in preparation for holiday period. Expectations rising for fourth quarter. China reports mainland July retail sales of gold, silver and jewelry up 22% year on year to CNY 24.7 billion ($3.65 billion).
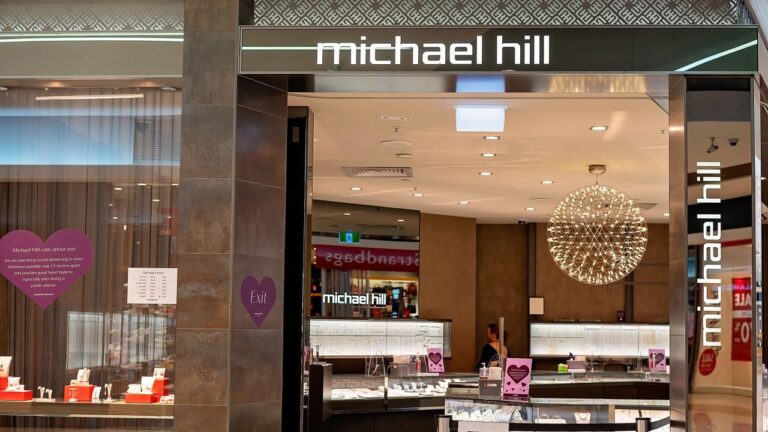
Michael Hill Reports Sales Rise Across All Segments
Same-store revenue up in Canada, Australia and New Zealand.
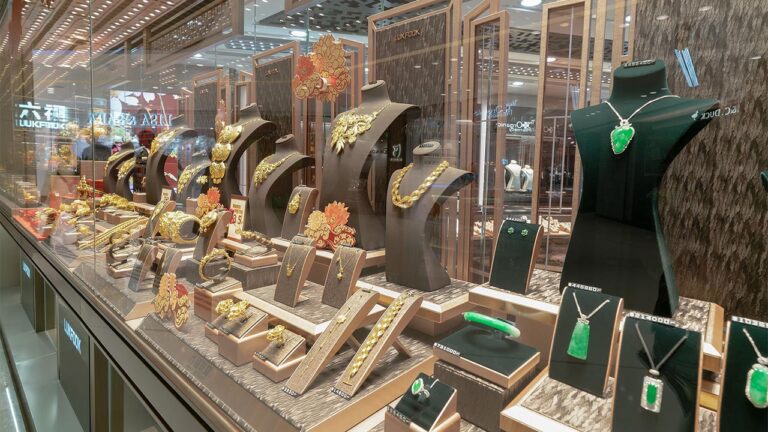
Luk Fook Revenue Rises as Diamond-Jewelry Demand Improves
Group opens store in London, entering European market for first time.
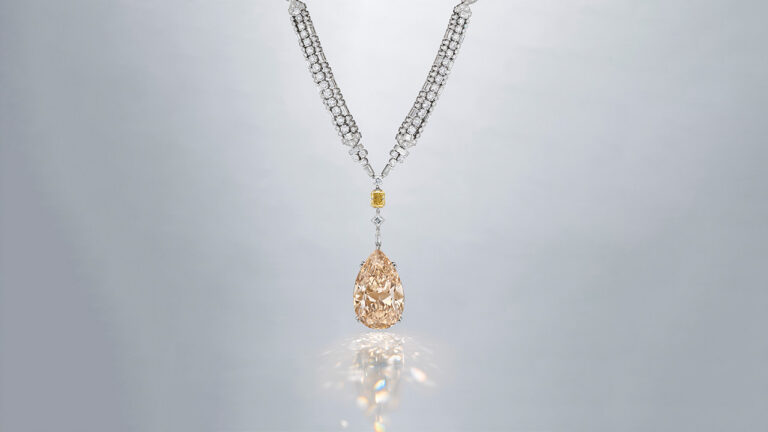
91ct. Starlight Diamond Necklace to Headline Christie’s Shanghai
William Goldberg jewel carries high estimate of $2.7 million.