Hong Kong show opens with rising expectations for
Chinese demand after Las Vegas demonstrates positive US market. Polished prices
firm for RapSpec A2+ diamonds, and buyers shifting to lower price points for
lower-quality goods. Limited inventory supporting prices for 3 ct. and larger diamonds.
Rough trading steady during De Beers sight, despite tight manufacturing profit
margins. Consolidation among cutters and dealers expected as high rough prices
reduce profitability. India May polished exports +8% to $2.2B. Antwerp’s AWDC
unveils automated polishing technology. Martin Rapaport issues statement
calling on De Beers to cancel its restriction on source disclosure.
Fancies: Fancy shapes mixed, with curves better than squares.
Ovals hot, followed by Emeralds, Pears and Cushions. Marquises and Princesses
weak. Oversizes selling well. Steady demand for fine-quality 6 to 10 ct. Ovals,
Pears and Emeralds, with prices firming for 3 to 5 ct. due to shortages. US
supporting market for commercial-quality, medium-priced fancies under 1 ct. Far
East demand improving as consumers seek fancy shapes at better prices.
Off-make, poorly cut fancies illiquid and hard to sell, even at very deep
discounts.
United States: Steady
New York dealer trading ahead of July break. Retail and wholesale performing better
than last year. Retailers limiting purchases to replacements for sold stock.
Jewelers focused on preparing collections for fall and holiday seasons. Below
0.30 ct., G-H, SI doing well, but difficult to find the right goods to fill
orders.
Belgium: Stable
demand, with shortages in select categories. Suppliers maintaining firm prices,
particularly for RapSpec A2+. Buyers shifting to VG to get better discount.
Liquidity concerns as banks continue to refuse diamond-industry lending. Rough
trading steady during De Beers sight, with boxes selling at mid-single-digit
premiums on the secondary market.
Israel: Optimistic
mood in the bourse. Focus shifts to Far East after Las Vegas shows.
Large orders for 1 ct., H-L, VVS2-SI2 from Hong Kong jewelers. Good demand,
with firmer prices for 1 ct., F-J, VS1-VS2. 0.50 and 0.70 ct. SIs improving.
India: Small
manufacturers struggling to source rough at current price levels. Weaker rupee
(INR 68 = $1) negatively impacting suppliers to the local market, but helping
exporters. Large manufacturers raising polished production to fill shortages.
New available output garners stronger prices than existing stock. Jewelry
retail sales stagnant.
Hong Kong: Dealers
focused on this week’s show (June 21 to 24). Jewelers increasing inventory and fueling
optimism for the fair. Retail buyers pushing for higher discounts for 0.30,
0.50 and 1 ct., D-G, VS, RapSpec A2+ goods. Suppliers holding prices firm for
those categories. Rising concern about De Beers’ entry into synthetic-diamond
jewelry.
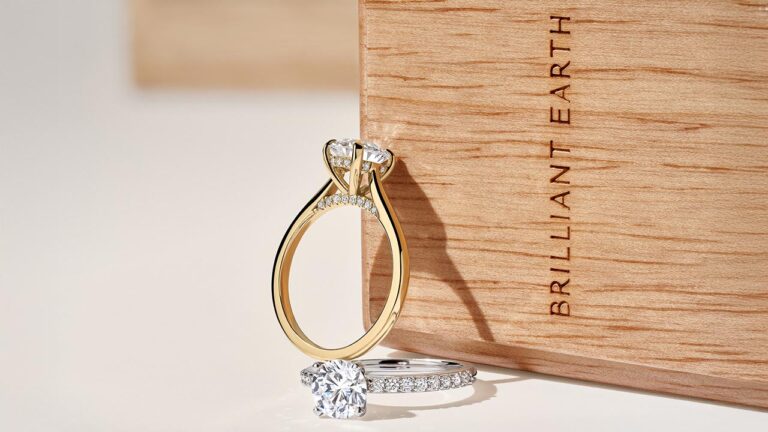
Brilliant Earth Sales Exceed Guidance
Brand’s diversification into more fine jewelry drives revenue increase.
Petra Sees Glimmer of Light Amid $20M Lifeline
Advance payment for future diamond inventory provides near-term liquidity to run business.
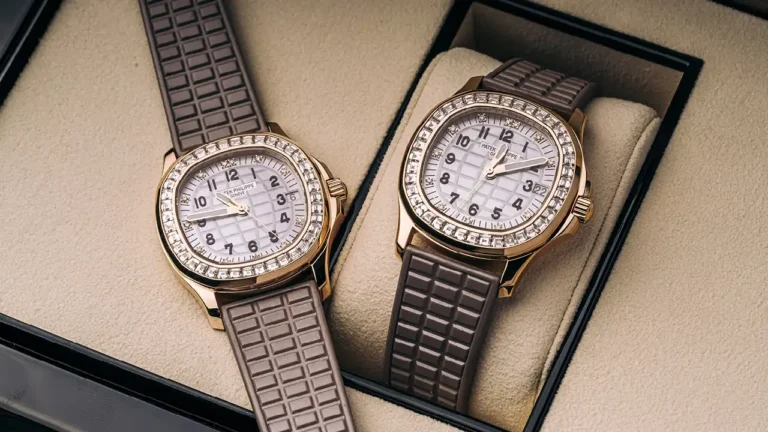
Can Diamonds Learn from Watches? Yes, But
Rough Notes: In many ways, timepieces had an easier job recovering from their crisis.