Summer lull continues, with some improvement as US
dealers return from vacation. Prices slightly softer due to seasonal slowdown. Suppliers
optimistic for 2H amid US and China jewelry growth, despite trade tensions. US
jewelers improving efficiency with customization and omni-channel as 477 retailers
closed in 1H vs. 445 last year. Indian cutters cautious due to weak rupee and tighter
credit, as banks cut lending -10% since alleged $2B Nirav Modi fraud. De Beers 1H
revenue +2% to $3.2B, underlying earnings -41% to $202M, rough prices +1.6%.
Alrosa 1H production -17% to 15.9M cts. LVMH 1H jewelry and watch sales +8% to
$2.3B. Federal Trade Commission classifies lab-grown as a diamond.
Fancies: Far East demand improving as Chinese consumers seek Pears and
Princesses at better prices. US and European demand mixed, with curves better
than squares. Ovals hot, followed by Emeralds, Pears and Cushions. Marquises
and Princesses weak. Oversizes selling well. Steady demand for fine-quality 6
to 10 ct. Ovals, Pears and Emeralds, with prices firming for 3 to 5 ct. due to
shortages. US supporting market for commercial-quality, medium-priced fancies
under 1 ct. Off-make, poorly cut fancies illiquid and hard to sell, even at
very deep discounts.
United States: Buyers slowly returning from vacation. Steady demand for 1.50 to
2.50 ct., G-J, VS-SI, RapSpec A3+ goods. Cushions improving. Dealers preparing
for New York Antique show. Retail sentiment positive, despite trade-war
fears.
Belgium: Dealers
preparing for vacation, with bourses set to close for three weeks (July 30 to
August 20). Suppliers holding firm on prices,
expecting stronger orders after August break. Steady demand and shortages for 3
ct., D-F, IF collections goods. 0.30 to 0.40 ct. selling well in Europe. Rough
trading stable during sight week.
Israel: Activity slowing ahead of bourse summer
vacation (August 5 to 17). Good demand for 3X, no-fluorescence diamonds. Steady
US demand for 1 ct., G-J, SIs. High-end fancy colors doing well,
commercial-quality yellows stable. Melee market quiet.
India: Fewer foreign
buyers in Mumbai during summer period. Trade cautious amid tight liquidity and
diminishing credit. Domestic demand weak due to higher rupee diamond prices
after currency depreciation. Steady demand for 1 ct., G-J, SI-I2, RapSpec A3+
diamonds. High rough prices squeezing manufacturing profits, with factories
operating below full capacity.
Hong Kong: Quiet market
expected until September show amid summer slowdown. Chinese tourists cautious
due to yuan depreciation. US tariffs on Chinese goods threatening consumer
outlook. Dossiers selling better than 1 ct.+ goods. Steady demand for 0.30 to
0.40 ct., G-J, VS-SI. Weaker demand for 1.50 to 2 ct. goods. Jewelers see
strong 2Q.
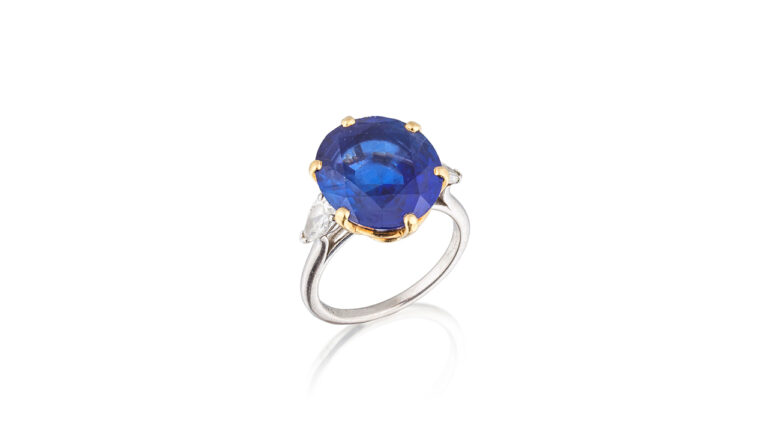
Cartier Sapphire Ring More Than Triples High Estimate at Bonhams
11.50-carat gemstone fetches $230,400 at recent Fine Jewellery auction in Paris.
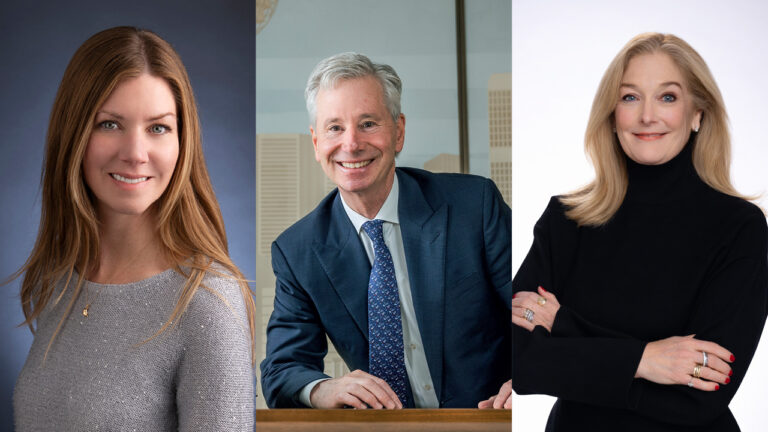
Jewelers of America Elects Three New Directors to Its Board
Lawrence Bock, Caryl Capeci and Amanda Coleman-Phelps will join executive team.
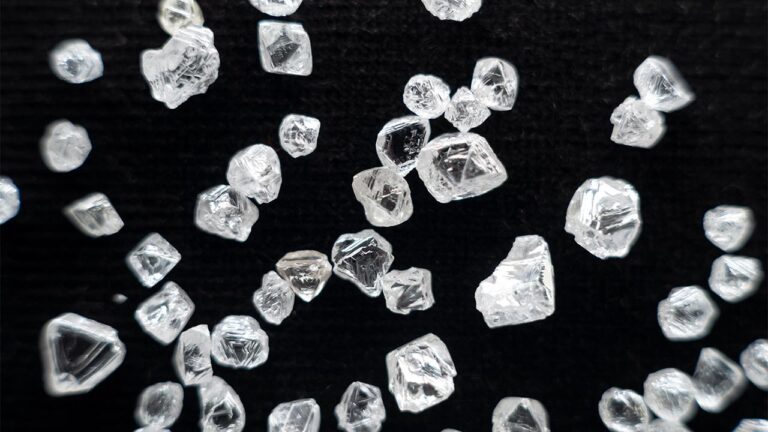
De Beers Holds Prices Steady at Small October Sight
Company sale looms amid quiet pre-Diwali trading.