RAPAPORT… Charm-bracelet maker Alex and Ani has filed for bankruptcy protection after accumulating high debts over the past few years.
The company, which operates 74 retail outlets across the US, Canada and Puerto Rico, has been mired in financial challenges since 2018, chief restructuring officer Robert Trabucco said in a June 9 filing.
The company’s rapid growth created operational difficulties, the filing noted. In addition, it experienced significant management turnover, including the exit of founder Carolyn Rafaelian, and defaulted on credit facilities, Trabucco said.
In 2019, Alex and Ani’s lenders appointed Trabucco to restructure the company. Shortly after that, the Covid-19 pandemic forced the jeweler to close all its stores, but the business remained responsible for paying its leases. This cocktail of challenges “placed significant stress on the company’s ability to operate and service its debt obligations,” Trabucco noted.
Alex and Ani currently has about $127.4 million in debt obligations, the Chapter 11 filing shows. It also owes $29.1 million in unsecured trade debts — money owed to vendors, suppliers and landlords. In addition, it is not receiving income from one-third of its retail network, which remains closed due to the virus.
Alex and Ani plans to sell some or all of its assets to repay its debt, Trabucco explained. As a backup plan, it will also work on a restructuring program that includes Rafaelian selling her 35% share of the company to The Bathing Club. Lion Capital, one of Alex and Ani’s debtholders, and now the majority owner of the company, will also sell The Bathing Club 35% of its first-lien debts, he added.
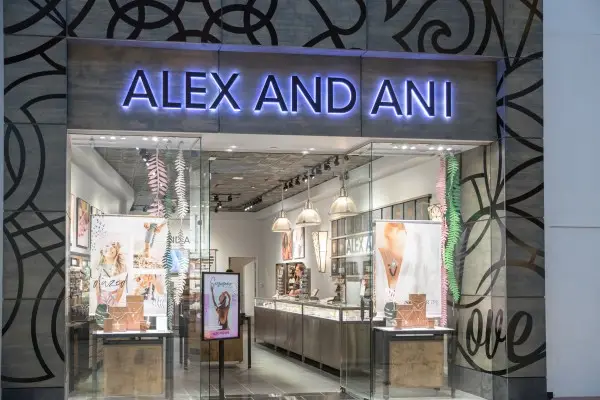
Image: An Alex and Ani store in Philadelphia, Pennsylvania. (Shutterstock)
Namibia Authorities Investigate Allegations About Corruption in Diamond Sector
Brilliant Star denies activist’s allegations about it; De Beers terminates company’s sight following separate review.
Shai Schnitzer Becomes Third Generation of Family to Head IDE
His grandfather, Moshe Schnitzer, and father, Shmuel Shnitzer, both served as president.
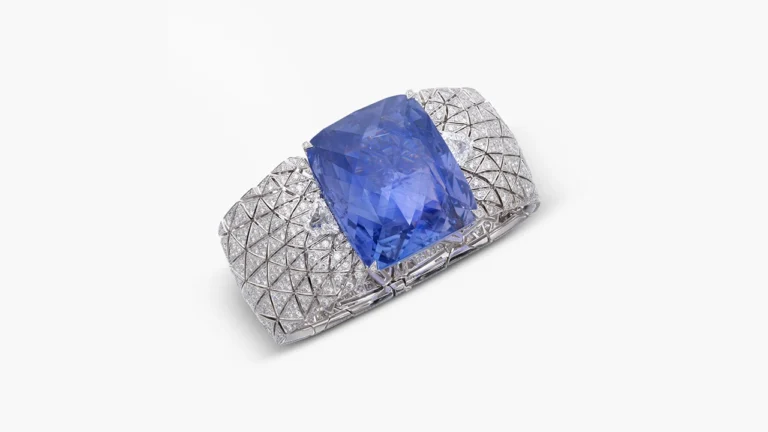
Romanov Sapphire Sails Past Estimate to Score $5M at Sotheby’s
Auction house originally predicted Cartier bracelet would bring in up to $2 million.