The views expressed in this article are those of the author and do not necessarily reflect the views of Rapaport or its editorial team.
The global diamond industry faces severe structural challenges, yet much of the trade remains bogged down in arguments over terminology. Accurate disclosure of synthetics at the point of sale is essential, which is why the United Arab Emirates (UAE) has raised differentiation within the Kimberley Process. However, terminology is a baseline for consumer protection rather than a complete business strategy. Disclosure tells buyers what they are looking at; it does not give them a reason to buy, or provide a retailer with a sustainable business model.
Language choice itself illustrates this divide. This article uses “synthetics” per the World Jewellery Confederation (CIBJO) centenary congress recommendation and ISO 18323 standards, while acknowledging that Federal Trade Commission (FTC) guidelines in the United States permit “laboratory-grown.” Regardless of which term dominates, the industry’s strategic priorities must shift from vocabulary to customer experience, product positioning, and unit economics.
Retail strategies worldwide show that category adoption and profitability are two very different achievements. Signet Jewelers integrated synthetics into established price points, with products containing synthetic stones reaching approximately 27% of merchandise sales in the financial year that ended January 31, 2026. Swarovski built a branded offering around custom cuts, doubling its Created Diamonds sales in 2024. Conversely, Pandora stopped buying mined diamonds in 2021, but its lab-grown revenue fell to 1.1% of the group total in 2025, with like-for-like sales declining 18% in the first half of 2026. This contrast demonstrates that an accessible fashion brand cannot easily elevate its price tier simply by incorporating cheaper stones. Meanwhile, De Beers used Lightbox to test price references before closing the unit in 2025 and redirecting its synthetic arm, Element Six, toward advanced industrial applications.
Furthermore, the common retail assumption that natural diamonds always yield higher transaction values remains untested at scale within the fashion segment. With small natural stones facing lower average realized prices per carat and acute provenance challenges in mixed parcels of melee, synthetics can sometimes offer higher retail margins and larger order values on the showcase floor.
Behind retail counters lies a highly concentrated, three-nation supply chain for gem-quality synthetics. China produces most rough (45% to 50%), India leads cutting and polishing, exporting nearly 15 million carats of polished synthetics in 2025, and the United States is the primary consumer market, where synthetic center stones reached 61% of the bridal market’s engagement-ring purchases in 2026. While headlines often conflate gem output with global industrial diamond production, which exceeded 15.5 billion carats in 2024, gem-quality supply remains tightly linked to this corridor, leaving it exposed to geopolitical, tariff, and energy risks. At the same time, production costs for synthetics have an underlying floor driven by raw-material consumables such as tungsten carbide and nickel, while growing demand in deep-tech sectors, including semiconductor thermal management, is increasingly diverting high-tier synthesis capacity away from retail jewelry.
In grading, divergent commercial paths have also emerged across major laboratories. HRD Antwerp halted quality certificates for loose commercial synthetics, the Gemological Institute of America (GIA) transitioned to descriptive “Premium” and “Standard” tiers, and the International Gemological Institute (IGI) maintained the full 4Cs, capturing roughly 65% of global synthetic certification. These differences are not a failure of standards requiring a forced compromise, but rather independent commercial choices.
Ultimately, natural diamonds and synthetics serve fundamentally different value propositions. Natural diamonds offer geological rarity, deep provenance, and cultural heritage, supported by a natural rough supply that fell to approximately 100 million carats in 2025, whereas synthetics offer design flexibility, industrial scale, and accessibility.
At the Dubai Multi Commodities Centre (DMCC), we have structured our operations accordingly, keeping our lab-grown segment separate from our natural-diamond and colored-gemstone platforms. Both sectors can thrive, provided the industry moves past semantic disputes and builds business models grounded in commercial reality.
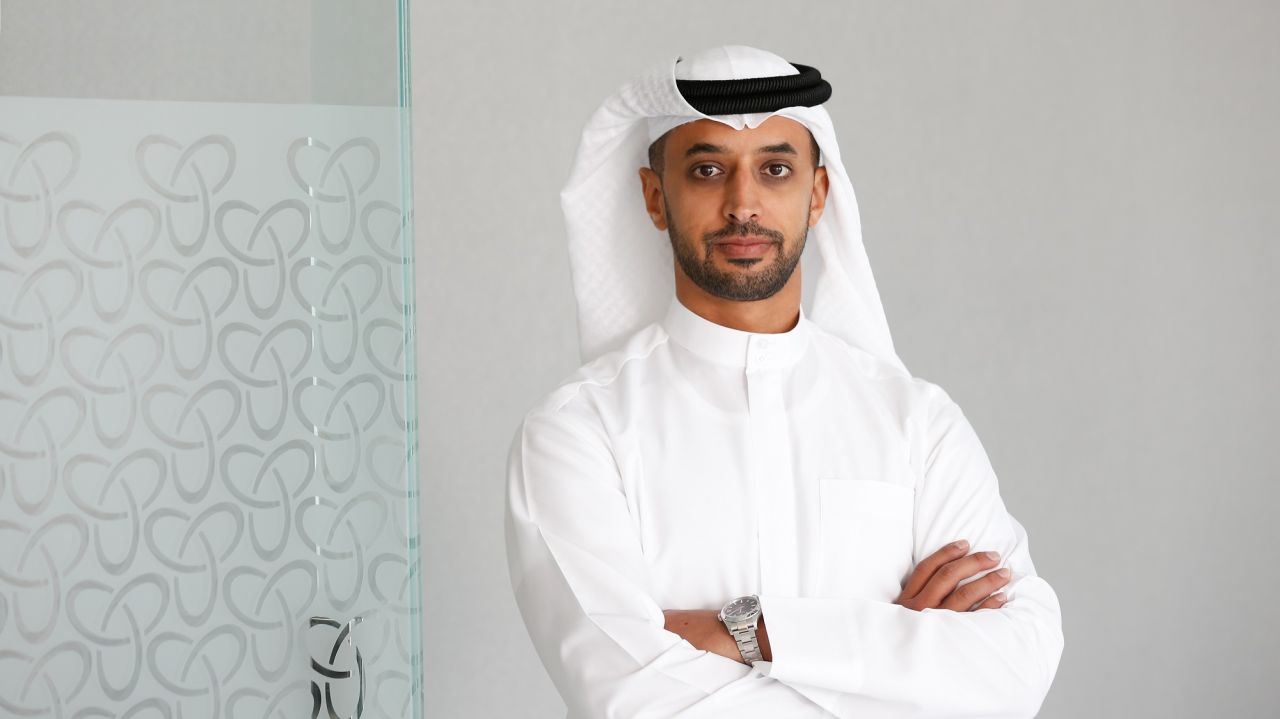
Ahmed Bin Sulayem is the executive chairman and CEO of the DMCC.
Image: Ahmed Bin Sulayem. (Dubai Multi Commodities Centre)